Top 5 Lenders for Car Repair Loans for Bad Credit in 2026
Last updated: 2026-10-16
Walking into a mechanic’s shop only to find out your transmission needs a complete overhaul is a gut punch. When the repair bill looks more like a mortgage payment, the stress can feel overwhelming. For many drivers, a sudden mechanical failure is a crisis that demands immediate cash to keep life moving.
A failed alternator might cost $400, but a transmission swap or an engine replacement can easily soar into the $3,000 to $5,000 range. This creates an immediate liquidity gap that most monthly budgets cannot absorb without planning. It is a sudden, sharp financial blow that catches most people off guard.
Finding a lender that accepts less-than-perfect credit scores is the primary goal for most people in this situation. When your credit score has been impacted by medical bills, student loans, or previous missed payments, traditional banking institutions often become inaccessible. You find yourself staring at a locked door when you need a way out.
This ranking focuses on speed, accessibility, and the reality of borrowing when your credit history isn’t your strongest asset. It is about getting back on the road without sinking further into a financial hole. We looked at how these lenders actually function when you are in a pinch.
- Manhattan Bank
- FastLendGo
- Addition Fi
- Minute Loan Center
- CreditNinja
How We Evaluated These Repair Financing Options
The selection process prioritized lenders that cater specifically to those facing unexpected automotive expenses. We looked for providers that offer quick turnaround times, which is critical when you need your vehicle for work or family obligations. Speed is often the difference between getting to a job and losing a paycheck.
If you are a delivery driver or a commuter with a long distance to travel, a three-day waiting period for funds might mean losing several shifts of income. This effectively increases the “true cost” of the loan. You aren’t just paying interest; you are paying for the time you spent without a car.
We also examined the breadth of loan products offered by each entity. A lender that provides various amounts, from small emergency sums to larger amounts, offers more flexibility for different repair scenarios. A simple brake pad replacement might only require a $300 quick loan.
Conversely, a blown head gasket might require $2,500. We looked for lenders that don’t force you into a massive loan if you only need a small fix, and those that can scale up for major structural repairs. The following comparison highlights the key features available for each provider based on their current service offerings.
| Lender Name | Loan Amounts | Funding Speed | Credit Requirements |
|---|---|---|---|
| Manhattan Bank | See site | See site | See site |
| FastLendGo | $500 – $5,000 | See site | Bad/Fair Credit |
| Addition Fi | Up to $5,000 | See site | See site |
| Minute Loan Center | See site | Same-day | Fair Credit |
| CreditNinja | See site | Same day* | Bad Credit |
The Best Lenders for Automotive Repairs
1. Manhattan Bank
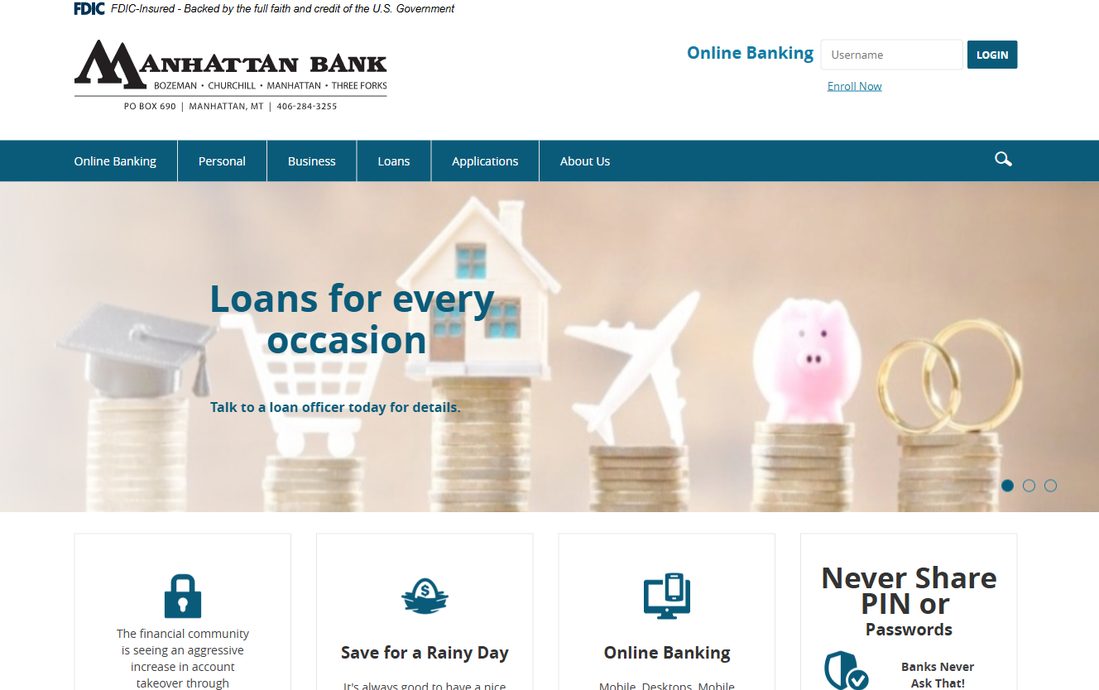
Manhattan Bank operates as a traditional banking institution with the security of FDIC insurance. This provides a level of peace of mind that many specialized online lenders simply cannot match. For those who prefer working with a formal bank structure, this is a solid option for various personal loan needs.
Because they are a full-service bank, they offer a more structured approach to borrowing. While this might mean a slightly more thorough vetting process—often involving a review of your debt-to-income ratio and employment history—the stability of an FDIC-insured institution is a massive advantage for long-term financial health.
When applying with a traditional bank, you are typically looking for a “Personal Loan,” which is unsecured. This means you don’t have to put your vehicle up as collateral, which is a significant relief if you are already struggling with car-related expenses. You can keep your title in your hand.
However, because they prioritize stability, they may require a more established banking history or a steady stream of documented income via pay stubs or W-2s. They want to see that your income is as reliable as their vaults.
Pros:- FDIC-insured security
- Established banking reputation
- Offers personal loans for many occasions
- May have more rigorous application requirements than quick-cash lenders
2. FastLendGo
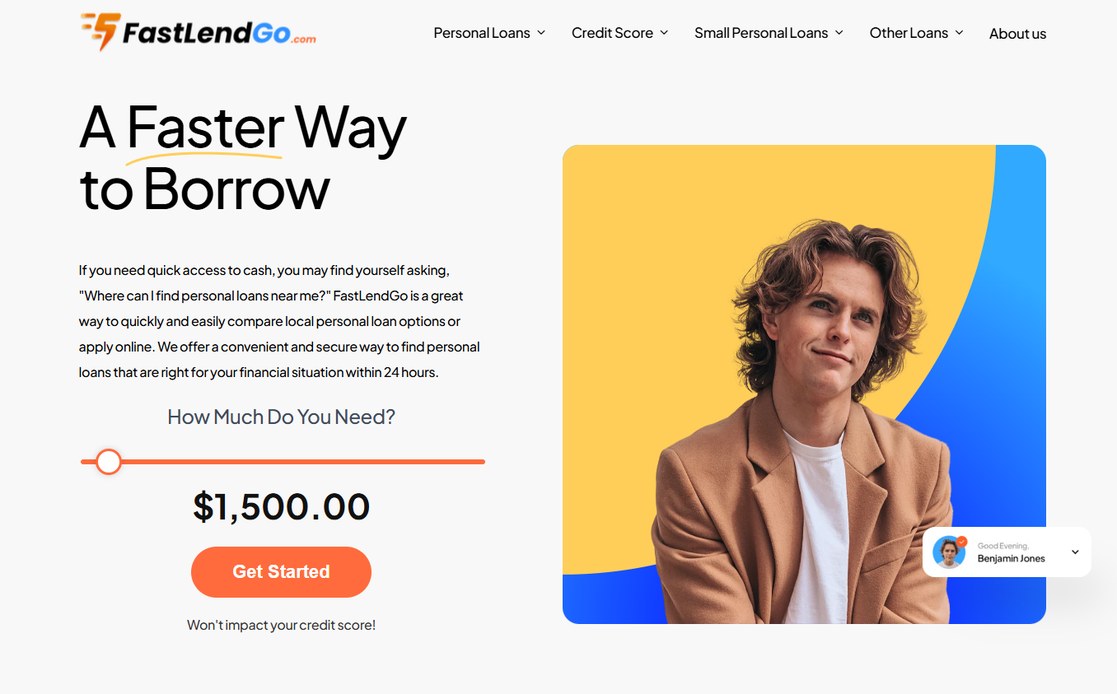
FastLendGo specializes in being a partner for those who might struggle with traditional bank requirements. They offer a wide range of specialized products, including specific options for auto repair loans and even motorcycle loans. This makes them a versatile choice for various mechanical emergencies.
Instead of trying to fit a square peg into a round hole with a general-purpose loan, FastLendGo‘s specialized products are tailored to the reality of automotive ownership. They understand that a car isn’t just a luxury; it is often a tool for survival.
With loan amounts ranging from $500 up to $5,000, they cater to both small fixes and larger, more significant engine repairs. This range is particularly useful for tiered repair needs. You can address the immediate crisis without over-borrowing.
For instance, if your mechanic says, “You need a new fuel pump now, but you can wait six months on the suspension,” FastLendGo allows you to borrow exactly what is needed for the immediate crisis. Their focus on high-speed access makes them a strong contender for anyone in a time-sensitive situation.
Pros:- Flexible loan amounts from $500 to $5,000
- Designed for bad and fair credit
- Limited to specific states
3. Addition Fi
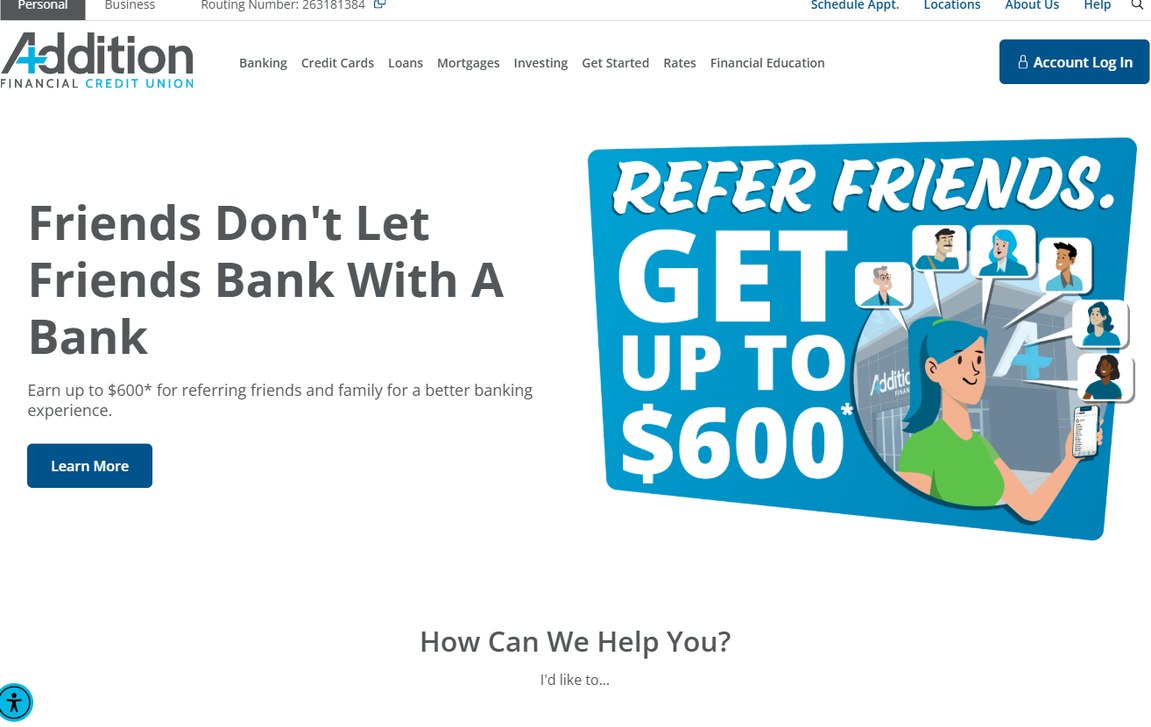
Addition Financial Credit Union offers a membership-based approach to personal banking. For those looking to build a long-term relationship with a financial institution, this is a standout choice. Credit unions are member-owned cooperatives, which often means they operate with a different philosophy than for-profit banks.
Their primary goal is to serve their members, which can translate to more personalized service and competitive terms. It feels less like a cold transaction and more like a community resource. They aren’t just looking at numbers on a screen; they are looking at people.
They offer competitive rates and a variety of loan products. While they are a broader credit union, their ability to help members “borrow smarter” makes them a reliable option for those who want to manage their debt responsibly while fixing their vehicle.
Because credit unions often have slightly more flexible underwriting criteria than large national banks, they may be more willing to look at the “why” behind a low credit score—such as a past medical emergency—rather than just the score itself. They see the human story behind the data.
Pros:- Credit union membership benefits
- Competitive rates for members
- Diverse range of financial products
- Requires membership to access full benefits
4. Minute Loan Center
When the car is stuck in the shop and the clock is ticking, Minute Loan Center offers a rapid response. They focus heavily on the speed of the application and the immediacy of the funds. Their model is built for people who need cash to be deposited as soon as the same business day.
This is a vital feature for those living paycheck to paycheck, where a three-day delay in funds could mean a late fee on rent or a missed utility payment. In these moments, every hour feels like a lifetime. They aim to cut that waiting time down to almost nothing.
The platform is designed to be straightforward, aiming to help users step into financial freedom through quick approvals. The digital-first approach means you can often complete the entire process from your smartphone while waiting in the mechanic’s lobby.
This is ideal for the driver who cannot afford to miss a day of work because their vehicle is sidelined and they need to authorize the repair immediately to get it back on the road. They prioritize getting you back to work, which keeps your income flowing.
Pros:- Same-day deposit potential
- Fast approval process
- User-friendly online application
- Approval is dependent on fair credit status
5. CreditNinja
CreditNinja acts as a bridge for those who find themselves unable to get approved by traditional lenders. Their system is designed to match users with loan options that fit their specific credit profile. It is a way to stop guessing and start knowing.
Rather than you spending hours applying to ten different lenders only to get ten rejections, CreditNinja uses a matching algorithm to point you toward the lenders most likely to approve your specific situation. It is a streamlined way to find a solution when other doors have closed.
The process is quick and simple, focusing on providing a fast decision. If you are in a pinch and need to know where you stand without a long, drawn-out waiting period, this is an efficient way to explore your options.
It acts as a powerful reconnaissance tool for anyone who is unsure of their eligibility in a high-pressure environment. It helps you narrow your search so you aren’t wasting energy on lenders that will simply say no.
Pros:- Same-day decision potential
- Quick and simple online application
- Targets those with bad credit
- Does not guarantee approval
Understanding the Total Cost of Borrowing
When you are in an emergency, it is easy to focus solely on the monthly payment, but this can be a dangerous trap. To truly understand your financial obligation, you must look at the Annual Percentage Rate (APR). This includes both the interest rate and any mandatory fees.
A loan with a “low” monthly payment might actually be more expensive over the long term if the interest rate is significantly higher than a standard bank loan. Don’t let a small number hide a large debt. Look at the grand total you will pay back by the end of the term.
Consider these three factors when reviewing a loan offer:
- The Repayment Term: A 24-month loan will have much lower monthly payments than a 12-month loan, but you will pay significantly more in total interest over that extended period.
- Origination Fees: Some lenders deduct a fee from the loan amount before you even receive it. If you need exactly $1,200 for a repair but the lender charges a $100 origination fee, you will only receive $1,100, leaving you short at the mechanic.
- Prepayment Penalties: If you receive a bonus at work or a tax refund and want to pay off the car loan early to save on interest, some lenders charge a fee for doing so. Always check if “prepayment is without penalty.”
Smart Steps to Prepare for Your Loan Application
Securing a loan under pressure is difficult, but being prepared can increase your chances of approval and better terms. Even if you are applying for a high-speed loan, having your documentation ready can prevent delays that could leave you stranded without transport.
Follow these steps to streamline the process:
- Gather Documents: Have your most recent pay stubs, a government-issued ID, and your bank account details (for direct deposit) ready. If you are self-employed, have your last two years of tax returns on hand.
- Get a Written Estimate: Do not guess the amount you need. Ask your mechanic for a detailed, written estimate that includes parts and labor. Borrowing too little leads to more debt later; borrowing too much leads to unnecessary interest.
- Check Your Own Credit: While you may have bad credit, knowing your score helps you understand which lenders (like CreditNinja or FastLendGo) are your most viable targets.
- Verify Your Income: Lenders want to see that you have the ability to repay. Even if your credit is poor, a stable, documented income is your strongest asset during the underwriting process.
Navigating your borrowing options requires a balance of urgency and caution. Before signing any paperwork, it is vital to look at the total cost of the loan. Interest rates can vary wildly between a traditional bank and a specialized lender. Always ask for the total amount you will be paying back over the life of the loan, not just the monthly payment.
Another common pitfall is rushing into a high-interest loan just to solve an immediate problem. While speed is important, an expensive loan today can become a heavy burden tomorrow. Compare your options carefully and ensure the repayment schedule fits comfortably within your monthly budget.
If a monthly payment would mean you can’t afford groceries or gas, the loan is too large or the term is too long. You shouldn’t have to choose between fixing your car and feeding your family. Take a breath and look at the math one more time.
Finally, read the fine print regarding any fees. Some lenders charge origination fees or prepayment penalties that can catch you off guard. Taking ten minutes to read the terms can save you hundreds of dollars in the long run, ensuring your car repair doesn’t lead to a financial disaster. Your goal is to get back on the road, not to remain stuck in a cycle of high-interest debt.