Top 5 Best Personal Loans for a 550 Credit Score in 2026
Last updated: 2026-10-16
Trying to manage money with a 550 credit score often feels like walking through waist-deep mud. It is a tough spot to be in, especially when life throws a sudden curveball your way. An unexpected car repair, an urgent dental bill, or a surprise medical cost can arrive exactly when your bank account is at its lowest.
Traditional banks might slam the door shut, treating a 550 score as an automatic disqualifier. However, several specialized lenders stay open for business. These companies use their own scoring models that look past your FICO number. They check your income stability, employment history, and even your banking relationships to see if you are a reliable borrower.
Finding a lifeline requires more than just glancing at the interest rate. You have to weigh how fast you get the cash against the total cost of the debt. Some people need a low APR to keep long-term costs down. Others just need the money in their account within 24 hours to avoid an eviction notice or a late fee.
This list highlights the most reliable options for anyone currently sitting in the fair to poor credit range. It provides a way to make sense of these high-stakes decisions when you need help quickly.
- LendingPoint
- FastLendGo
- Max Cash
- Avant
- Reprise
How These Lenders Were Evaluated
Evaluating lenders for low credit scores means looking past the marketing gloss. The main focus is accessibility and whether you can actually get funds despite a difficult credit history. It is not just about finding a company that says yes. It is about finding a company that offers a fair way to say yes.
A lender might boast a high approval rate, but they aren’t a true lifeline if their terms include hidden service fees or predatory prepayment penalties. You need to know exactly what you are signing up for before you commit to the debt.
Our selection process focused on lenders catering specifically to the 550 range. We looked at three main areas: accessibility, speed, and transparency. We checked how fast they deliver funds, how clear they are about loan amounts, and the variety of products they offer. Every entry was vetted to ensure they provide real pathways for immediate relief.
We also tested the digital interfaces. If you are facing an emergency, you need to be able to complete the entire application from a smartphone while on the go. An interface that is hard to use can be a major roadblock when time is of the essence.
| Lender Name | Loan Amounts | Credit Requirements | Funding Speed |
|---|---|---|---|
| LendingPoint | $1,000 – $36,500 | Fair Credit | Fast Funding |
| FastLendGo | $500 – $5,000+ | Bad/Fair Credit | Quick Access |
| Max Cash | $250 – $10,000+ | Bad Credit | In Minutes |
| Avant | See site | 550 and above | Fast Funding |
| Reprise | See site | See site | See site |
1. LendingPoint

LendingPoint helps people move from financial stress toward a bit more stability. They offer a wide range of loan amounts, making them a versatile choice. You might need a small amount for a medical bill or a much larger sum to consolidate debt.
If you are carrying $15,000 in high-interest credit card debt, your monthly payments can start to spiral out of control. A single consolidation loan from LendingPoint can simplify everything into one predictable monthly payment. It is a way to stop chasing multiple due dates every month.
This lender works well for people tackling specific burdens like home improvements or debt. Their digital experience is streamlined to respect your urgency. You can upload documents and get a decision in minutes, which is vital when you are managing a very tight budget.
Pros:
- High maximum loan ceiling up to $36,500.
- No impact on credit score when checking rates.
- Versatile loan purposes including wedding and travel.
Cons:
- May have stricter requirements than specialized bad credit lenders.
2. FastLendGo

FastLendGo is built for the person who needs cash yesterday. They focus on quick access for needs like auto repairs or dental financing. If your car’s alternator fails and you need it fixed by Monday to keep your job, their specialized products are designed for that exact situation.
They occupy the space between traditional banking and high-interest payday loans by providing structured personal loans. This gives you more stability than a short-term cash advance but more speed than a standard bank loan.
Whether you need a $500 boost or a $5,000 loan, they offer various tiers. This flexibility matters when your score is in that tricky 550 zone. Instead of being forced into a massive loan you cannot afford, you can opt for a smaller amount that fits your immediate crisis.
Pros:
- Covers a wide range of specific emergencies like roof or motorcycle loans.
- Offers very small loan amounts for immediate needs.
- Provides options for high-income individuals and first-time borrowers.
Cons:
- The variety of products can be overwhelming for some.
3. Max Cash
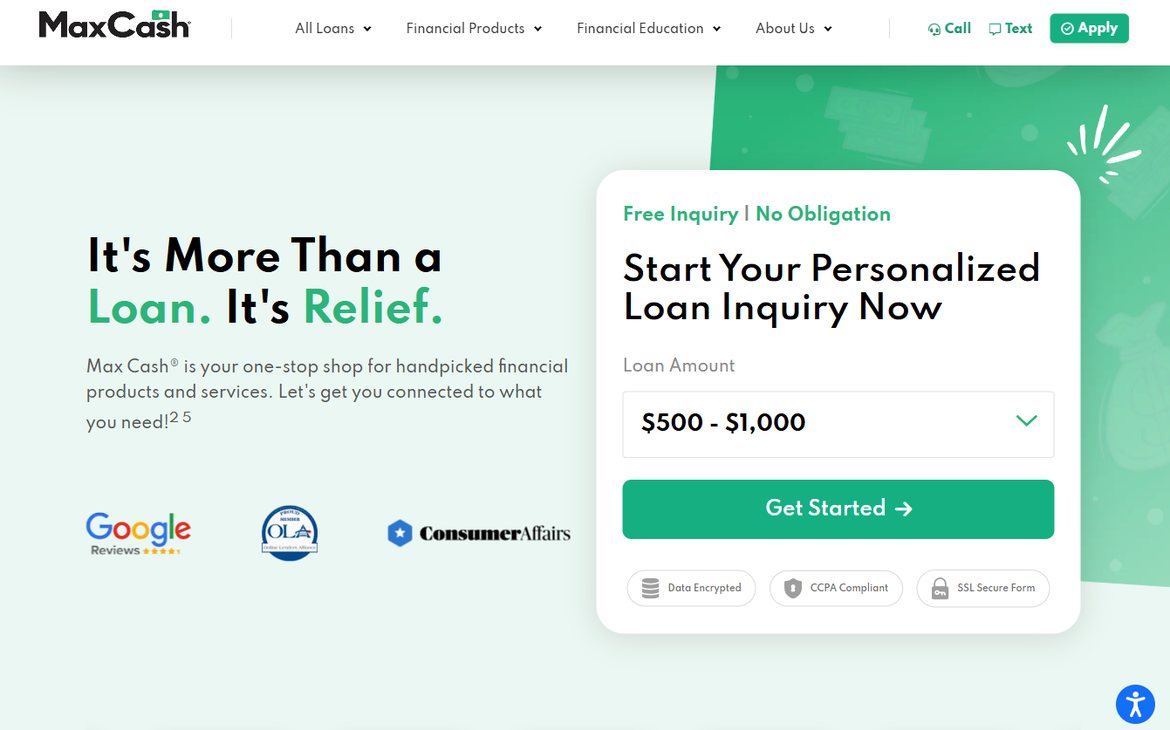
Max Cash acts as a matching service to find you relief. For those struggling with a 550 score, they offer a way to find personalized lender matches. Their system connects you with what you actually need, which saves you from searching through dozens of different websites.
Instead of a one-size-fits-all approach, they use an algorithm to find the lender most likely to approve your specific profile. It is about efficiency rather than just throwing a net into the water and hoping something sticks.
They specialize in highly accessible amounts, starting as low as $250. This is perfect for micro-emergencies where a large loan would be overkill. If you have a $300 utility bill, taking out a $3,000 loan would be a mistake. Max Cash lets you solve the small problem without the heavy burden of excessive interest.
Pros:
- Extremely low entry point for loan amounts.
- Fast inquiry process with no obligation.
- Handles a wide variety of credit situations.
Cons:
- Focus on small amounts may not suit major debt restructuring.
4. Avant

Avant is a major player for anyone looking to move forward financially. They are known for considering applicants with scores as low as 550. This makes them a vital option if you have been told no by the big-name traditional banks.
Unlike some lenders that only care about your FICO score, Avant looks at a broader view of your financial health. This can be a game-changer for people who have had recent setbacks but still maintain a steady income.
The lender is geared toward long-term solutions like debt consolidation or home improvements. If you apply before their afternoon cutoff, you might see funds hit your account remarkably quickly. Their platform is designed for the modern consumer who wants to manage everything from a mobile app.
Pros:
- Specifically caters to the 550 credit score demographic.
- Fast funding capabilities for approved applicants.
- Offers both credit cards and loans for different needs.
Cons:
- Approval is heavily dependent on specific timing and criteria.
5. Reprise
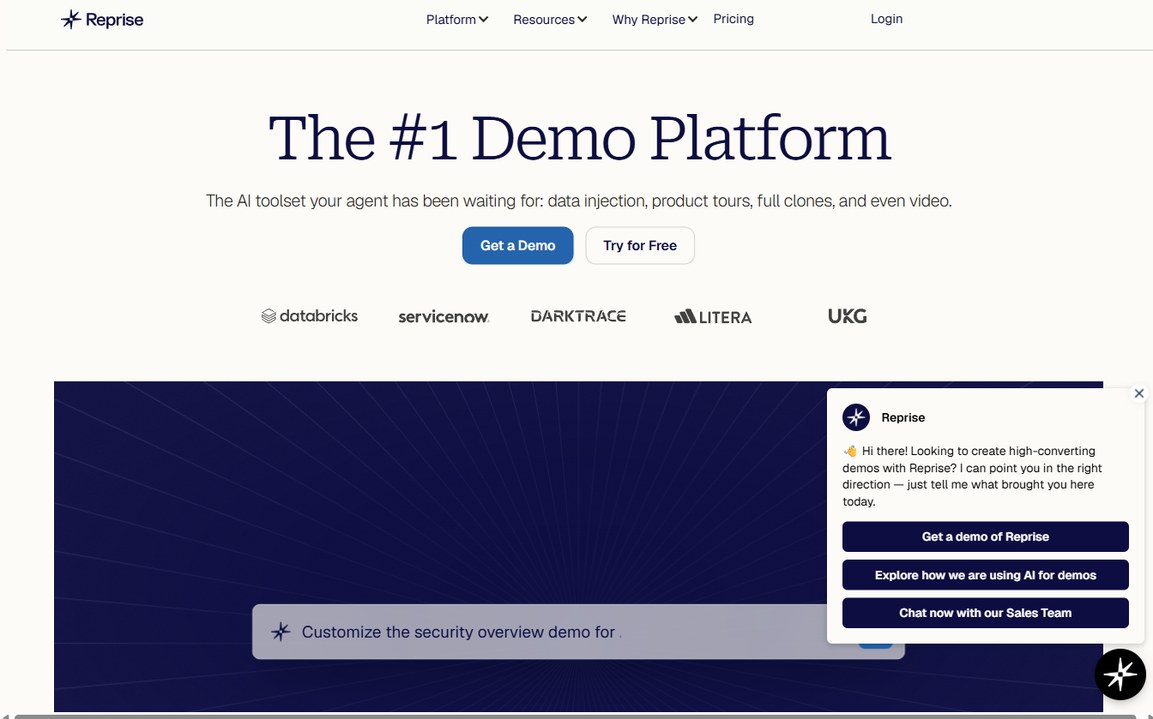
Reprise operates in a different sphere, focusing on high-tech solutions and AI-driven tools. It is not a traditional consumer personal loan lender like the others. Instead, it represents the newer side of financial technology and data management.
They are best suited for businesses or tech-forward entities looking for advanced demo creation and data injection. It is a specialized tool for those who need to present complex data in an interactive way, rather than a standard consumer seeking quick cash.
For a fintech startup looking to demonstrate how a loan application process works to potential investors, Reprise offers the tools to build that interactive experience. It is about the technology behind the scenes rather than the consumer at the counter.
Pros:
- Highly advanced AI toolset for demo creation.
- Efficient data injection and presentation capabilities.
- Allows for easy sharing of product tours.
Cons:
- Not a traditional personal loan provider for individual consumers.
Understanding the Cost of Borrowing: APR vs. Monthly Payment
When you are in a financial bind, it is easy to fall into the trap of shopping only for the lowest monthly payment. You might see two loan offers: one with a $50 monthly payment and another with a $75 monthly payment. The $50 option looks like the winner because it leaves more money in your pocket today.
However, this is a dangerous way to evaluate debt. The true cost is found in the Annual Percentage Rate (APR). A lender might offer a low monthly payment by stretching the term of the loan out over seven years. While your monthly obligation is lower, you could end up paying double or triple the amount you originally borrowed due to the interest.
Always ask: “What is the total amount I will have paid back by the time this loan is finished?” If that number is significantly higher than the principal, you are paying a massive premium for the convenience of a lower monthly payment.
The Impact of Hard vs. Soft Credit Inquiries
A critical piece of knowledge for anyone with a 550 score is understanding how the application process affects your rating. There are two types of inquiries: soft pulls and hard pulls. A soft pull occurs when a lender checks your credit to see if you are pre-qualified. This happens when you use “check your rate” features.
These inquiries do not show up on your credit report to other lenders and they do not lower your score. They are essentially a way to window shop without any penalty.
A hard pull occurs when you officially submit an application for a loan or credit card. This signals to the credit bureaus that you are actively seeking new debt, which is seen as a risk factor. Each hard pull can cause a small, temporary dip in your score. If you are trying to repair your credit, you want to minimize these pulls.
How to Choose and Avoiding Pitfalls
Choosing a lender is a bit like picking a pair of shoes; if they don’t fit right, you’re going to have a painful journey. Always look at the total cost of the loan, not just the monthly payment. A low monthly payment might hide a massive interest rate that will drain your wallet over time.
You should always request a truth-in-lending disclosure. This is a legal requirement that clearly outlines the total finance charge and the total amount you will eventually pay back. It takes the guesswork out of the equation.
One of the biggest mistakes people make is applying for multiple loans all at once. This creates a “shotgun” effect where several hard inquiries hit your report in a short window. This makes you look desperate to creditors and can further tank your score. Instead, pick one or two lenders that match your specific need and focus there.
Finally, read the fine print. Ensure you understand the repayment terms and check for prepayment penalties. Some lenders charge you a fee if you try to pay the loan off early. You don’t want to be stuck in a high-interest trap when you are finally ready to be debt-free. Use these lenders as a tool for recovery, but use them wisely.